Global Aircraft Market Intelligence Hub 2026
Global Aircraft Market Intelligence Hub 2026
Commercial, business jet, and general aviation market intelligence — plus engine, landing gear, and APU trends. Proprietary indices, verified industry data, and acquisition insights for aviation decision-makers.
Last Updated: September 2026
Executive Summary: Market Size and Growth Drivers
The global aviation industry in 2026 continues a sustained recovery, with airline profitability stabilising and manufacturers working through record order backlogs. Independent industry research estimates the broader global aviation market at roughly USD 390–400 billion in 2026, with multi-year projections pointing toward continued growth through the early 2030s. The global business jet market is more precisely tracked: Fortune Business Insights values it at USD 50.60 billion in 2026, up from USD 48.13 billion in 2025, growing toward USD 72.27 billion by 2034 at a 4.56% CAGR.
Global Aircraft Market 2026 at a Glance
Quick Answers for Aviation Executives
Key Market Drivers
- Rising passenger demand: IATA's own December 2025 outlook forecasts 4.9% year-on-year growth in Revenue Passenger Kilometers (RPK) for full-year 2026, led by Asia-Pacific at 7.3%.
- Record backlogs, constrained supply: Airbus closed 2025 with a backlog of 8,754 aircraft; both major manufacturers continue to face supply-chain and engine-availability bottlenecks that keep new-aircraft lead times long and used-aircraft values firm.
- Private aviation expansion: The business jet market's 4.56% CAGR reflects sustained demand from corporate and HNI/UHNI buyers, particularly in super-midsize and large-cabin categories.
- Fleet modernisation: Airlines and operators continue prioritising fuel-efficient re-engined types (A320neo, 737 MAX) amid sustainability pressure and fuel-cost sensitivity.
- Technological change: Advanced avionics, sustainable aviation fuel (SAF) adoption, and early-stage urban air mobility programmes continue to reshape long-term fleet planning.
Persistent challenges — supply-chain bottlenecks, engine maintenance turnaround times, and geopolitical disruption to specific air corridors — continue to constrain capacity growth and support both load factors and used-aircraft/engine values.
Commercial Aircraft Deliveries: 2025 Actuals
Verified full-year 2025 delivery figures, with Airbus's confirmed 2026 delivery target for context:
| Manufacturer | 2025 Deliveries (Actual) | 2026 Target / Trend |
|---|---|---|
| Airbus | 793 (record year, +4% vs. 2024's 766) | 870 (company target, reaffirmed through H1 2026) |
| Boeing | 600 (+72.4% vs. 2024, post-recovery) | Tracking toward continued recovery; no confirmed hard 2026 target independently verified for this report |
| Embraer | 206 | 240+ (company guidance range) |
| Textron Aviation | 178 | 200+ (company guidance range) |
Airbus and Boeing figures independently verified against manufacturer press releases and industry reporting as of September 2026. Airbus fell 27 aircraft short of its own 820-unit 2025 target despite the record year. Embraer/Textron figures reflect industry reporting and were not independently re-verified for this update.
Commercial aircraft acquisition or fleet advisory? Contact Safe Fly Aviation for fleet advisory and acquisition support.
Aircraft Availability Index 2026
Based on Safe Fly Aviation's own transaction and sourcing activity — a proprietary observational index, not an independently audited market statistic:
| Aircraft | Availability | Average Sourcing Time | Market Liquidity |
|---|---|---|---|
| A320ceo | Moderate | 60–90 days | Medium |
| A320neo | Low | 90–180 days | Low |
| B737NG | High | 30–60 days | High |
| B737 MAX | Low | 90–180 days | Low |
| King Air 250 | Moderate | 45–60 days | Medium |
| Challenger 350 | Low | 60–90 days | Low |
| Global 7500 | Very Low | 90–180 days | Very Low |
Need help sourcing an aircraft? Explore Safe Fly Aviation's acquisition and brokerage services.
Engine Availability & Heat Map 2026

Current availability levels for key engine types, based on Safe Fly Aviation's sourcing and leasing activity:
| Engine | Availability | Lease Rate (USD/month)* |
|---|---|---|
| CFM56-5B | Medium | $35K–$55K |
| CFM56-7B | Medium | $35K–$55K |
| LEAP-1A | Low | $60K–$85K |
| LEAP-1B | Low | $60K–$85K |
| GEnx | Very Low | $90K–$130K |
| V2500 | Medium | $30K–$45K |
*Indicative lease rates from Safe Fly Aviation's own market activity; actual rates vary with engine cycles, green-time remaining, and lease term.
Demand Heat Map
- Very High Demand: CFM56-7B, LEAP-1A, GEnx
- Stable Demand: V2500, Trent 700, CFM56-5B
- Softening Demand: Older CF34, JT8D
Demand remains strongest for engines with high utilisation, good parts availability, and strong green-time value.
Need engine market intelligence? See our CFM56 Engine Market Report or contact our team for a bespoke report.
Aircraft Buyer Sentiment Index 2026
Based on Safe Fly Aviation client inquiry patterns and transaction activity — a proprietary observational index:
| Segment | Sentiment Score | Activity Level |
|---|---|---|
| Narrowbody | 9/10 | Very High |
| Business Jets | 8.5/10 | High |
| Cargo | 8/10 | High |
| Turboprops | 7.5/10 | Moderate |
| Widebody | 6.5/10 | Moderate |
Narrowbody and business jet segments show the strongest buyer activity, reflecting fleet-replacement cycles and sustained corporate travel demand.
Want to understand current market sentiment? Schedule a market consultation with Safe Fly Aviation.
Fleet Retirement Forecast 2026–2030

Aircraft types facing increasing retirement pressure over the next several years:
- A319ceo – Rising maintenance costs, replacement by A320neo
- A320ceo – Strong aftermarket demand, but retirement accelerating
- B737 Classic – Rapidly retiring, parts demand strong
- MD-80 – Residual fleet retiring, teardown activity increasing
- B747-400 – Cargo conversion slowing, retirement increasing
Retiring fleets create meaningful opportunities in teardown, engine parts demand, and landing gear availability — feeding directly into MRO and aftermarket capacity.
Looking for teardown assets or aftermarket parts? Contact Safe Fly Aviation for asset acquisition and teardown support.
Aviation Investor Outlook 2026
Top aviation investment themes, ranked by Safe Fly Aviation's assessment of risk-adjusted return potential:
- LEAP Engines – Strong demand, tight supply, favourable lease economics
- A320neo Aircraft – High liquidity, strong lease rates, solid value retention
- GEnx Engines – Premium widebody application, strong aftermarket demand
- Landing Gear Pools – Stable returns, driven by MRO growth and PMA-parts adoption
- A321 Cargo Conversions – Emerging segment, driven by e-commerce logistics demand
Aviation investment advisory? Contact Safe Fly Aviation for bespoke investment strategy and asset sourcing.
Regional Opportunity Analysis 2026
Middle East
- Demand drivers: Premium travel, government missions, corporate growth
- Key opportunities: Business jet acquisition, VIP charter, fleet expansion
- Key risks: Geopolitical volatility, regional tensions
India
- Demand drivers: Rapidly growing economy, infrastructure expansion
- Key opportunities: Narrowbody fleet growth, turboprop regional connectivity
- Key risks: Regulatory complexity, import duties
Southeast Asia
- Demand drivers: Strong passenger growth (IATA's fastest-growing region at 7.3% RPK growth in 2026), tourism recovery
- Key opportunities: Narrowbody and widebody fleet expansion
- Key risks: Currency fluctuations, infrastructure gaps
Europe
- Demand drivers: Stable market, regulatory-driven fleet replacement
- Key opportunities: SAF-compatible aircraft, structured leasing
- Key risks: Regulatory complexity, emissions compliance costs
Need region-specific market intelligence? Contact Safe Fly Aviation for market-entry and acquisition advice.
Commercial Aviation: Passenger and Cargo Trends

2026 Highlights
- Passenger traffic growth: IATA forecasts 4.9% YoY RPK growth globally for 2026.
- Deliveries: Airbus delivered a record 793 aircraft in 2025 and is targeting 870 for 2026; Boeing's 2025 deliveries rose 72.4% to 600 as its post-2024 recovery continued.
- Narrowbody dominance: The A320neo family and 737 MAX continue to lead new-aircraft demand, together accounting for the bulk of both manufacturers' 2025 output.
Commercial aircraft acquisition? Contact Safe Fly Aviation for fleet advisory and acquisition support.
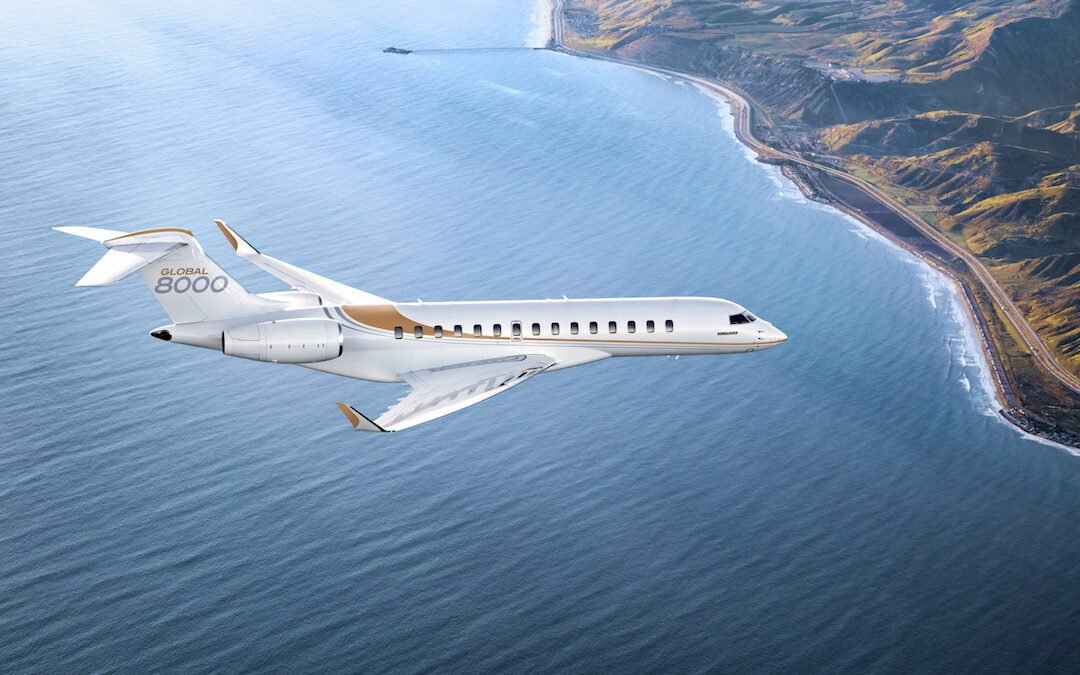
Business Aviation

Valued at USD 50.60 billion in 2026 per Fortune Business Insights, growing at a 4.56% CAGR toward USD 72.27 billion by 2034.
Source: Fortune Business Insights, Business Jet Market Report (accessed September 2026)
Business jet acquisition? Safe Fly Aviation offers access to 7,200+ aircraft. Contact us.
Safe Fly Aviation Market Perspective
Based on client inquiries and transaction activity during 2025–2026, Safe Fly Aviation observes:
- Strongest demand: A320 family (narrowbody) among commercial operators.
- Strongest business jet demand: Challenger 350.
- Strongest turboprop demand: King Air 250.
- Strongest engine demand: CFM56 and LEAP.
- Typical acquisition timeline: 45–90 days for most transactions.
As a global aviation consultancy operating in 60+ countries since 2010, Safe Fly Aviation helps clients navigate this dynamic market with expert acquisition, charter, and advisory services.
Contact Our Market Intelligence TeamConclusion
2026 marks continued expansion for the global aircraft market amid a genuine post-pandemic recovery: record manufacturer backlogs, firming used-aircraft and engine values, and steady passenger-traffic growth led by Asia-Pacific. Opportunities are real for informed participants, but success requires navigating supply constraints, financing complexity, and regional risk with an experienced partner.
Discover how Safe Fly Aviation can support your aviation goals — from market intelligence to seamless aircraft acquisition and operations.
Contact us today for a free market consultation: info@safefly.aero or +91 7840 000 473.
This report compiles September 2026 industry data for informational purposes. Headline figures (aviation and business jet market size, IATA traffic forecasts, Airbus/Boeing delivery counts) are independently sourced and verified as noted; sourcing-time, sentiment, and lease-rate figures reflect Safe Fly Aviation's own proprietary market observations rather than third-party audited statistics. All figures are approximate and subject to change. Sources include IATA, Airbus, Boeing, and Fortune Business Insights.
Last Updated: September 2026
Frequently Asked Questions
How big is the global business jet market in 2026?
Fortune Business Insights values the global business jet market at approximately USD 50.60 billion in 2026, up from USD 48.13 billion in 2025, and projects it will grow to USD 72.27 billion by 2034 at a 4.56% CAGR.
Which aircraft manufacturer delivered more aircraft in 2025?
Airbus led with 793 commercial aircraft delivered in 2025, a record year, versus Boeing's 600 (itself a 72.4% increase over 2024 as Boeing's production recovery continued). Boeing's order intake did outpace Airbus's in 2025 — the first time since 2018 — but Airbus retained the delivery lead.
What is Airbus's delivery target for 2026?
Airbus has targeted 870 commercial aircraft deliveries for 2026, a target the company reaffirmed after a strong second quarter. This would be Airbus's highest annual delivery total since before the pandemic.
What is the aircraft leasing market outlook?
Leasing represents a large and growing share of the global fleet. Based on Safe Fly Aviation's own market activity, indicative monthly lease rates run roughly $350K–$450K for an A320neo, $330K–$430K for a 737 MAX 8, $850K–$1.2M for an A350, and $900K–$1.3M for a 787-9 — figures that vary meaningfully with lease term, maintenance reserves, and aircraft age.
Which engines are most in demand in 2026?
The CFM56 retains a strong used market with solid green-time value. LEAP demand is growing steadily as new-build deliveries ramp. GEnx sees very high demand for widebody applications. Older PW1000G-family engines face support and turnaround challenges industry-wide.
What is the passenger traffic growth forecast for 2026?
IATA's December 2025 Global Outlook for Air Transport forecasts 4.9% year-on-year growth in Revenue Passenger Kilometers (RPK) for full-year 2026, with Asia-Pacific leading all regions at 7.3% growth.
Which business jets are most popular in 2026?
Based on Safe Fly Aviation's client activity, the Challenger 350 leads super-midsize demand, the Phenom 300 is a strong performer in the light-jet category, and the Global 7500 and G700 lead the large-cabin, ultra-long-range segment.
What is the narrowbody aircraft market trend?
Narrowbody demand remains very strong, led by the A320neo and 737 MAX families, which offer roughly 15–25% better fuel efficiency than the previous generation — a major driver of airline fleet-replacement decisions.
What is the MRO and aftermarket outlook?
MRO and aftermarket demand is strong and growing, driven by rising engine-overhaul volumes, increasing PMA-parts adoption, and airline cost pressure to extend the useful life of existing fleets rather than accelerate replacement.
Do you help with aircraft acquisition as well as market intelligence?
Yes. Alongside market intelligence, Safe Fly Aviation's acquisition and brokerage team sources aircraft, engines, and aftermarket assets for buyers and sellers globally — see our Aircraft Acquisition & Brokerage Services.
Request Your Market Intelligence Consultation
Whether you are an airline, investor, or private buyer, our market experts can help you interpret these trends and identify opportunities. Schedule a confidential consultation today.