Why Turboprops Dominate Regional African Aviation | Market Analysis 2026
Why Turboprops Dominate Regional African Aviation
Africa's short, thin, and often unpaved regional routes favor turboprop aircraft over regional jets — and manufacturer, operator, and cost data explain why that advantage is widening in 2026.
Key Takeaways for Aviation Executives
Across Africa's vast and varied landscape, one aircraft category keeps proving indispensable: the turboprop. From the savannahs of East Africa to the deserts of the Sahel, turboprops connect communities that jets cannot economically or physically reach. This analysis looks at the operating economics, runway performance, and fleet data behind that dominance — and where the industry's own numbers, not marketing claims, actually point.
1. The Economic Case: Fuel Is the Real Divide
The clearest evidence for turboprop economics in Africa isn't a marketing percentage — it's what a real operator's cost sheet looks like during a fuel-price shock. When jet fuel prices across Africa surged in early 2026, reaching around $171 a barrel on the Platts index, FlySafair (South Africa's largest low-cost carrier, which flies an all-Boeing 737 fleet) reported that fuel had risen to 50-55% of its direct operating costs — against a roughly 20-25% global industry average cited by the African Airlines Association (AFRAA). Turboprops don't eliminate fuel-price exposure, but their 30-40% lower fuel burn per block hour than a similarly sized regional jet cushions that exposure meaningfully on Africa's short sectors.
Why This Matters More in Africa Than Elsewhere
Roughly 70% of Africa's imported aviation fuel transits the Strait of Hormuz, making the continent unusually exposed to Middle East supply disruptions. A regional turboprop network that burns 30-40% less fuel per block hour than an equivalent regional jet fleet is not just cheaper day-to-day — it is structurally less exposed to exactly the kind of price shock African carriers experienced in 2026.
2. Runway Performance: Where Jets Simply Can't Go
Much of rural Africa has no paved runway at all, and building one is expensive and slow. Turboprops are built for exactly this gap. The manufacturers' own certified performance figures make the case without needing an "unpaved airstrip count" that no public database actually verifies at the continent level.
| Aircraft | Takeoff Field Length | Landing Field Length | Source |
|---|---|---|---|
| DHC-6 Twin Otter (STOL) | 366 m (1,200 ft) | 320 m (1,050 ft) | De Havilland Canada, official brochure |
| ATR 72-600 | 1,279 m (4,196 ft) | 915 m (3,002 ft) | ATR, official factsheet |
| Dash 8-400 | 1,277 m (4,188 ft) | 1,268 m (4,160 ft) | De Havilland Canada, official spec sheet |
| Beechcraft 1900D | 1,057 m (3,470 ft) | 1,422 m (4,667 ft) | GlobalAir aircraft specifications |
Figures are sea-level, standard-day, maximum-weight performance from each manufacturer's own published specifications — actual field requirements vary with elevation, temperature, and payload, which matters even more at Africa's high-altitude airports (see Section 5).
3. Maintenance & Support
Turboprop MRO support in Africa is more developed than it might appear from outside the continent. ATR and De Havilland Canada both maintain active parts and field-support relationships with African operators, concentrated around established aviation hubs such as Johannesburg, Nairobi, and Addis Ababa. Regional jet MRO, by contrast, more often requires ferrying aircraft to Europe or the Middle East for heavy checks — a real cost and downtime disadvantage that compounds on thin regional routes where an aircraft out of service for weeks is harder to absorb.
4. Fleet & Operator Landscape — What's Actually Flying
Reliable, current, aircraft-level fleet data is harder to find for African carriers than for major global airlines, so the table below only includes figures independently verified against each airline's own fleet page, Wikipedia's sourced fleet tables, or a manufacturer/press release — not estimates.
| Country | Operator | Verified Turboprop Fleet | Source |
|---|---|---|---|
| Ethiopia | Ethiopian Airlines | 30 × Dash 8-400 (no ATRs currently — its ATR 42-300s were retired) | Ethiopian Airlines fleet data, Nov 2025 |
| Kenya | Jambojet (Kenya Airways subsidiary) | Dash 8-Q400 fleet, reported at 9 aircraft as of its most recent expansion announcement | Industry press (CAPA/ch-aviation) |
| Senegal | Air Senegal | 2 × ATR 72-600 | Air Senegal's own fleet page |
| South Africa | CemAir | Mixed Dash 8, CRJ, and Beechcraft 1900 fleet (exact current count not independently confirmed) | CemAir's own materials |
| Tanzania | Precision Air | 8 aircraft, all-turboprop: 3 × ATR 42, 5 × ATR 72-500 | Precision Air fleet data |
A correction worth flagging
An earlier version of this article listed FlySafair alongside Kenya Airways as a Dash 8-400 operator. That's incorrect — FlySafair operates an all-Boeing 737 fleet and has no turboprops. The carrier is included above only because its own reported fuel-cost data (Section 1) is genuinely useful context for the turboprop economics case, not because it flies turboprops itself.
5. Why Regional Jets Struggle in Africa
Regional jets aren't absent from Africa, but several structural factors work against them on the continent's shorter, thinner routes.
Hot-and-High Airports
Addis Ababa Bole International sits at 2,334 m (7,625 ft) elevation and Johannesburg's O.R. Tambo at 1,694 m (5,558 ft) — both well above sea level. Thinner air at altitude cuts into any aircraft's payload-range performance, but turboprops' shorter, more flexible field requirements give operators more margin to work with at these airports than a comparably sized regional jet.
Fuel Cost Exposure
As Section 1 shows, fuel can run 50%+ of direct operating cost for a jet operator in Africa during a price spike — turboprops' 30-40% lower block-hour fuel burn is a real structural advantage precisely when it matters most.
Underserved Route Economics
ATR's own market analysis puts more than 300 African city pairs without a direct air link today, and estimates 60% of the addressable routes are better suited to 70-seat turboprop capacity than to a larger regional jet.
6. Outlook: A Real, Documented Growth Trend
Rather than project a specific fleet-size forecast that no public source actually supports, the clearest evidence of turboprop momentum in Africa is what's already happened: ATR's own count of its in-service Africa fleet has grown roughly 30% over the past three years to more than 120 aircraft, driven by new operators (three separate carriers introduced ATRs in Kenya within an 18-month span) and existing fleet expansion (Air Algérie ordered 16 ATR 72-600s for a new domestic subsidiary). Continued growth in intra-African trade under the African Continental Free Trade Area (AfCFTA), and the roughly 300 city pairs ATR itself identifies as underserved, both point toward continued turboprop demand — though Safe Fly Aviation would caution against treating any single-digit-precision "aircraft by 2035" forecast as more certain than the industry data actually supports.
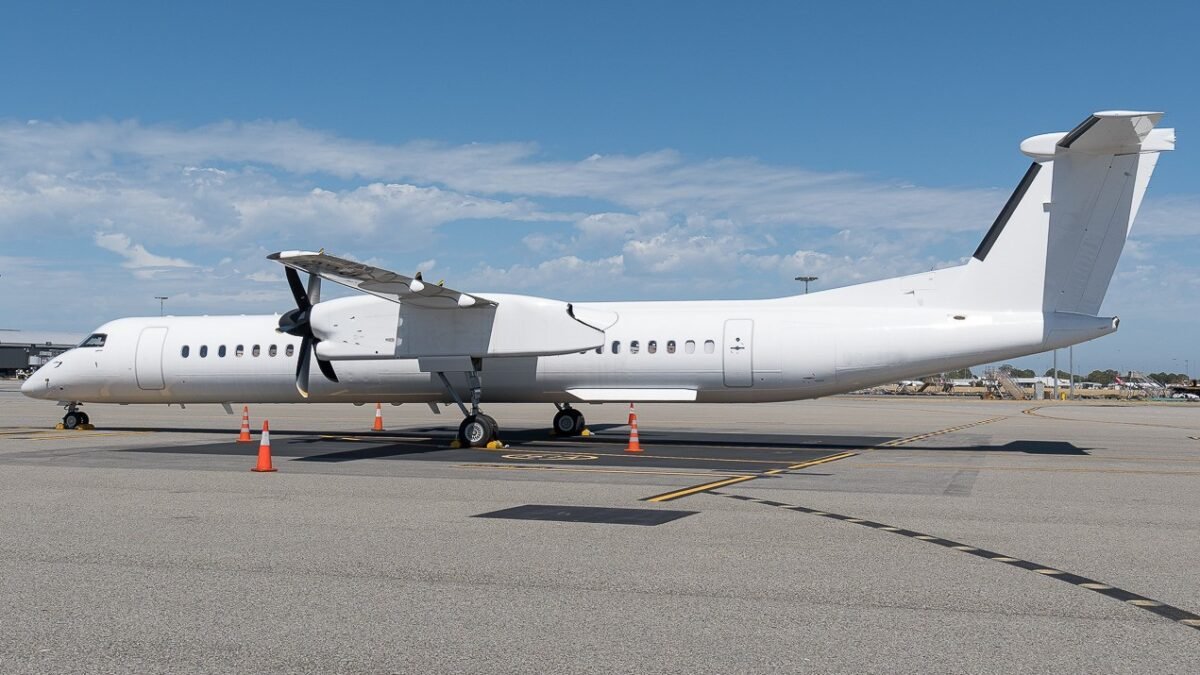
Turboprop Types Serving African Routes


References & Sources Cited
- ATR — "Building Bridges Across Africa's Skies" (Africa fleet size, growth, underserved routes)
- Ecofin Agency — African jet fuel price analysis, 2026 (fuel cost share, Platts pricing)
- ATR 72-600 official factsheet (runway performance)
- De Havilland Canada Dash 8-400 spec sheet (runway performance)
- De Havilland Canada Twin Otter Classic 300-G brochure (STOL performance)
- Ethiopian Airlines fleet data (Wikipedia, sourced fleet table)
- Addis Ababa Bole International Airport and O.R. Tambo International Airport (elevation data)
Turboprop Acquisition & Charter Advisory for African Operations
Safe Fly Aviation helps clients evaluate, acquire, and charter turboprop aircraft — including ATR, Dash 8, and King Air platforms — for African regional operations, backed by real fleet and route data, not marketing estimates.
Request a Briefing Turboprop Acquisition AdvisoryFrequently Asked Questions
Why can't regional jets compete effectively in Africa?
Regional jets typically need longer paved runways than turboprops, burn more fuel per block hour, and lose more payload-range performance at Africa's higher-elevation airports such as Addis Ababa (2,334 m) and Johannesburg (1,694 m). Turboprops' shorter field requirements and lower fuel burn make them a better economic fit for the continent's shorter, thinner regional routes.
Which turboprop models are most common in African fleets?
The ATR 72-600 and De Havilland Dash 8-400 are the most widely operated regional turboprops on the continent. ATR alone counts more than 120 aircraft now flying across Africa, up roughly 30% over the past three years. The DHC-6 Twin Otter and Beechcraft 1900D remain important for shorter-field utility and charter work.
How much shorter is a turboprop's runway requirement than a jet's?
It varies by type. A DHC-6 Twin Otter can take off in as little as 366 m under STOL configuration, and an ATR 72-600 needs about 1,279 m — both well under what most regional jets require on paved runways, and turboprops are far more tolerant of unpaved or semi-prepared strips, which cover much of rural Africa.
Why is fuel cost such a big factor for African operators right now?
African jet fuel prices spiked to around $171 a barrel in 2026 on Platts pricing, driven partly by the continent's exposure to Middle East supply routes — roughly 70% of Africa's imported aviation fuel transits the Strait of Hormuz. For at least one major African jet operator, fuel rose to 50-55% of direct operating cost, roughly double the ~20-25% global average cited by AFRAA. Turboprops' lower block-hour fuel burn reduces exposure to exactly this kind of shock.
Can Safe Fly Aviation help with turboprop charter or acquisition in Africa?
Yes. Safe Fly Aviation advises on turboprop charter and acquisition — including ATR, Dash 8, and King Air platforms — for operators and clients working across African regional routes. Contact info@safefly.aero or +91 7840000473 for a briefing.
Fleet, performance, and pricing figures in this article are compiled from manufacturer specification sheets, airline-published fleet data, and industry reporting cited above, and are accurate to the best of our research as of September 2026. Aircraft-level fleet counts for African carriers change frequently and are not all independently auditable — always confirm current fleet status directly with the operator before relying on it for a commercial decision. All content, images, and logos used on this page are for informational and illustrative purposes only; Safe Fly Aviation does not claim ownership of third-party logos or trademarked images unless otherwise stated, and such materials remain the property of their respective owners. If any copyrighted material is used incorrectly, please contact us and we will promptly correct it.