Russian Aviation Under Sanctions 2026: Fleet, Groundings, MC-21
Are sanctions grounding Russian aviation in 2026?
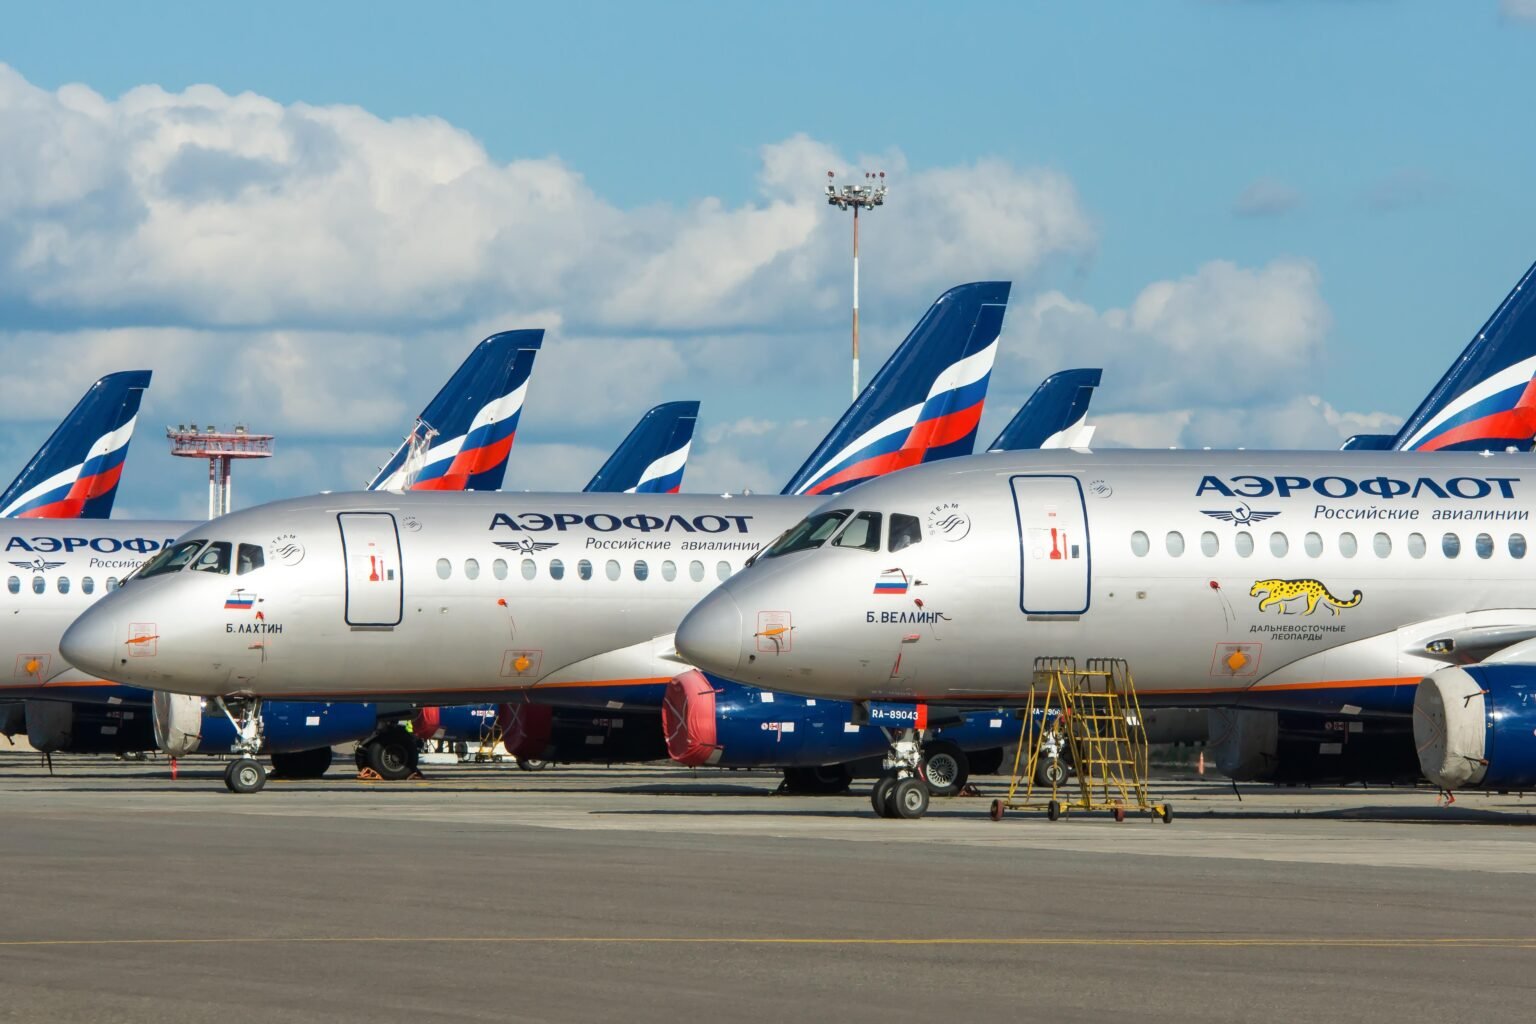
Not wholesale, but they are wearing it down. Russian airlines still fly 838 passenger aircraft, 460 of them Western-built, by cannibalising parked jets, buying parts through intermediaries and repairing more at home. The cost shows: a Kommersant analysis found about one in five aircraft at Russia’s 11 largest airlines out of service in summer 2026, and replacement aircraft are years late. The MC-21-310 now targets certification in early 2027, the SJ-100 first deliveries in the second half of 2027, and only 13 new Russian-built civil aircraft arrived between 2022 and 2025.
Russian aviation under sanctions: the 2026 picture
When Russia launched its full-scale invasion of Ukraine in February 2022, the EU, US, UK and others banned the supply of aircraft, engines and parts to Russia and cut off manufacturer support. Russian aviation had been built on Western technology: RFE/RL reported in January 2026 that around 75% of the commercial fleet was built in the US, the EU or Canada. The predictions of a quick collapse proved wrong, but four and a half years on the sector is running in a costlier, riskier and more improvised form.
This report brings together the latest public figures on the Russian airline fleet, the 2026 groundings, the parts and maintenance crisis, the delayed MC-21, SJ-100 and Il-114-300 programmes, and what all of it means for lessors, engine buyers and parts traders outside Russia. It complements our companion analysis, have sanctions actually weakened Russian aviation?, which looks at the metrics, route network and cost side in more depth.
Russia’s fleet in 2026: how many aircraft are flying
Two counts are in circulation and they measure different things. Cirium data from April 2026, reported by AirwayBuzz, puts the passenger fleet at 838 aircraft operated by 46 airlines, of which 460 are Airbus and Boeing types. Rosaviatsiya, the Russian regulator, reported a wider commercial fleet of 1,135 aircraft with 1,088 operational, in figures cited in October 2025. The second figure takes in all commercial types and regional and cargo operators, so it should not be compared directly with the first.
Whichever count is used, the direction is the same. Reuters, citing ch-aviation, found that factories were meant to build 5 civil aircraft in 2023, 40 in 2024 and 82 in 2025, yet only 13 new aircraft were added between 2022 and 2025. Rosaviatsiya head Dmitry Yadrov has said the fleet could lose 109 foreign-made aircraft by 2030, with a pessimistic case of about 339 aircraft, including old Russian types, leaving service. Rostec chief Sergei Chemezov said in March 2025 that at least 200 Western-built passenger aircraft would have to be replaced by 2030.
Demand has not collapsed. Aeroflot Group carried 26 million passengers in the first half of 2026, up 0.3%, with domestic traffic down 2.9% to 19.1 million and international traffic up 10.3% to 6.9 million, at a load factor of 90.9%. Full aircraft are the other face of a shrinking, ageing fleet: capacity is tight, so the strain falls on the aircraft that remain.
Groundings by airline: the 2026 Kommersant data
The clearest picture of sanctions strain is the Kommersant analysis reported by The Moscow Times on 29 June 2026. It found about one-fifth of the aircraft at Russia’s 11 largest airlines out of service during summer 2026, and nearly 30% once Aeroflot Group is excluded. Airlines with many newer Western-built aircraft, especially A320neo, A330 and 777 types, struggled most to obtain engines, parts and maintenance.
| Airline | Share of fleet out of service | What was reported |
|---|---|---|
| Azur Air | about 74% | Only 6 of 23 aircraft cleared to fly after regulator inspections found serious engine problems |
| Nordwind | about 44% | Includes several long-haul Airbus A330 and Boeing 777 aircraft |
| S7 | about 32% | Mainly engine problems on Airbus A320neo aircraft |
| Azimut | about 21% | Said it was operating all available aircraft after scheduled maintenance |
| Ural Airlines | about 20% | No detail reported |
| Red Wings | about 19% | No detail reported |
| Utair | about 15% | No detail reported |
| Aeroflot Group | about 11% | Most idle aircraft belonged to subsidiary Rossiya |
| Aeroflot (mainline) | about 4% | Mainline carrier only |
| Pobeda | about 0% | Operating its entire fleet |
Source: Kommersant analysis as summarised by The Moscow Times, 29 June 2026. Percentages are approximate and depend on how each airline’s fleet is counted; this is a secondhand summary and not a regulator’s dataset.
Sanctions timeline: 2022 to 2026
- 2022Lease terminations and closed skies. The EU banned the sale or supply of aircraft and parts to Russia in late February, and lessors were ordered to terminate leases by 28 March. The EU announced a ban on Russian-owned, registered and controlled aircraft in its airspace in early March. Airbus and Boeing suspended parts and support. Over 400 leased aircraft worth almost $10 billion remained in Russia after the deadline, and AerCap alone wrote off 113 aircraft and 11 engines.
- 2023Workarounds appear. Cannibalisation of parked aircraft is reported, and Aeroflot is reported to have sent an Airbus to Iran for maintenance.
- 2024The engine bottleneck. Kommersant reports 34 of 66 A320neo-family jets out of service in November, with S7 worst hit.
- 2025Replacement targets missed. Chemezov says at least 200 Western-built aircraft must be replaced by 2030. The US Department of Justice charges three people over about $2 million of aircraft parts exported to Russia. The first fully import-substituted MC-21-310 flies in October, and a production-standard SJ-100 flies in September.
- 2026Reactivations and delays. Older types return to service, the Il-114-300 is certified in June, Kommersant reports a fifth of major-airline aircraft idle, and the MC-21-310 and SJ-100 slip into 2027. The EU’s 21st package in July adds bans on aerospace metal powders and alloys.
The parts and maintenance crisis
The core problem is keeping Western-built aircraft airworthy without legitimate access to certified parts or manufacturer technical support. Four workarounds dominate public reporting.
- Cannibalisation. Airlines park some aircraft, including newer ones, to harvest components for others. The same logic is reported across several carriers and aircraft types.
- Intermediary supply chains. Parts are reported to reach Russia through third countries. The February 2025 US Department of Justice case over about $2 million of exported parts shows how enforcement tracks these flows.
- Domestic and third-country repair. Russian carriers have expanded in-country maintenance, and Aeroflot is reported to have used Iranian facilities for an Airbus in 2023. Quality and traceability are harder to verify than for OEM-approved shops.
- Reactivating older fleets. According to Izvestia in January 2026, 12 aircraft were due back in service in 2026, including Il-96, Tu-204/214 and An-148 types and Boeing 747s, for which spare parts are more plentiful.

Engines are the tightest constraint. Modern engine types need OEM-approved overhaul tooling, software and life-limited parts, none of which a workaround supply chain can replace at scale. That is why S7 and Azur Air, with large numbers of newer aircraft, were hit hardest in the 2026 data. For the supply side of this story outside Russia, see our aircraft engine shortages report and the guide to life-limited parts (LLP).
Safety and operational strain
Safety evidence is harder to quantify than fleet counts. Kyiv Post, drawing on Reuters and other reporting, noted that Russia recorded its highest number of aviation incidents in six years in 2024, and that Russia says its airspace is closed to its airlines in 37 countries. Separate from sanctions, drone strikes have repeatedly closed Russian airports: in July 2025 at least one airport closed almost every day, according to the same article.
What can be said with confidence is structural. A fleet that depends on cannibalised parts, non-OEM repairs and ageing airframes has less margin than one maintained to manufacturer standards. The regulator’s inspections of Azur Air, which cleared only 6 of 23 aircraft after finding serious engine problems, show regulators acting on engine findings, and they also show how thin the margin has become.
Domestic aircraft: MC-21, SJ-100 and Il-114
Sanctions cut Russian manufacturers off from Western engines, composites, avionics and machine tools, forcing every new programme to be redesigned around domestic parts. The result is a set of aircraft that are technically progressing, but years behind schedule.
| Programme | Type | Latest status | Next milestone |
|---|---|---|---|
| Yakovlev MC-21-310 | Narrow-body, PD-14 engines | About one-third of the certification flight campaign complete (May 2026). First fully import-substituted aircraft flew in October 2025. | Certification hoped for Q1 2027; mass production targeted for 2027 |
| Sukhoi SJ-100 | Regional jet, PD-8 engines | Production-standard PD-8 aircraft first flew September 2025. The 12 deliveries planned for 2026 will be missed (September 2026). | First production delivery H2 2027; type certificate expected spring 2027 |
| Ilyushin Il-114-300 | Regional turboprop, up to 68 seats | Type certificate issued 5 June 2026. No production aircraft confirmed delivered as of mid-August 2026. | First three aircraft to Arctic Airlines via lessor GTLK; first transfer expected by end-2026 |
Sources: Air Data News (MC-21 on 8 May 2026, SJ-100 on 18 September 2026, Il-114-300 on 16 August 2026), reporting statements by Rostec chief Sergei Chemezov, Minister Anton Alikhanov and First Deputy Prime Minister Denis Manturov. Dates are official targets as of 27 October 2026 and have slipped repeatedly before.
Yakovlev MC-21-310

The MC-21 was the flagship of Russia’s import-substitution drive. Its original MC-21-300 version used Pratt & Whitney engines and Western composites and systems. After sanctions it was redesigned around the Aviadvigatel PD-14 engine and Russian composites and avionics. The first fully import-substituted aircraft flew in October 2025. Chemezov said in May 2026 that about a third of the certification flight campaign was done and that certification could finish in the first quarter of 2027, later than his earlier estimate of the end of 2026. The United Aircraft Corporation aims to build 36 MC-21s a year by 2030.
Sukhoi SJ-100 and Il-114-300
The SJ-100 replaces the SaM146 engine with the Russian PD-8. After a production-standard aircraft flew in September 2025, Chemezov said in September 2026 that the first production aircraft will be delivered in the second half of 2027, ending hopes of the 12 deliveries planned for 2026. The Il-114-300 turboprop received its type certificate on 5 June 2026 and is slated to go first to Arctic Airlines under a lease from GTLK, but no production aircraft was confirmed delivered by mid-August 2026.
Wider industry problems persist: shortages of machine tools and skilled staff, and repeatedly missed production plans. Russia’s ambition of about 1,000 domestic commercial aircraft by 2030, quoted in 2025, looks far out of reach against 13 deliveries in four years.
What it means for aircraft, engine and parts markets
The Russian situation affects aircraft values, leasing and parts markets well beyond Russia. The points below are Safe Fly’s analysis of public reporting and our own market work, not forecasts of specific prices.
- Lessors and aircraft values
- The 2022 write-offs, including AerCap’s $2.7 billion pre-tax charge and a $3.5 billion insurance claim, showed how quickly a large market can disappear from a lessor’s books. Aircraft that remain in Russia are effectively lost to the global lessor market, which removes mid-life narrow-body capacity such as the Airbus A320 family. See our aircraft appraisal methods.
- Engines
- CFM56 and V2500 engines still power much of the older narrow-body fleet worldwide, so demand for overhaul slots and spare engines stays strong. See the CFM56 market report and V2500 supply shortage.
- Used serviceable material
- Aircraft teardowns remain a key source of parts, but the risk of counterfeit or unapproved parts entering the supply chain is a concern where provenance is unclear. Traceability matters more than price.
- Compliance
- Sanctions rules have grown with each EU package, most recently the 21st in July 2026. Brokers, lessors and MROs face higher due-diligence expectations on ownership, routing and end use.
For buyers, the lesson is to treat provenance as a core part of an aircraft or engine deal. Our aircraft engines for sale and pre-owned aircraft market trends pages explain how Safe Fly sources and documents assets, and the aircraft escrow process explains how funds are protected during a transaction.
What to watch next
- End of 2026: whether the first Il-114-300 is actually handed to Arctic Airlines, as GTLK has said it expects.
- First quarter of 2027: MC-21-310 certification, the date Chemezov currently targets.
- Spring and second half of 2027: an SJ-100 type certificate, then the first production delivery.
- From 2027: Kommersant’s experts expect aircraft availability to worsen as engines and components reach the end of their service lives.
- By 2030: Rosaviatsiya’s own projections of 109 to about 339 aircraft leaving service.
- Sanctions policy: further EU packages and enforcement cases, which keep reshaping what is possible in parts and MRO supply.
“Sanctions have not grounded Russian aviation, but they have raised its cost, slowed its replacement programmes and pushed it into a more improvised way of operating.”
Safe Fly Aviation Intelligence Desk, October 2026
Compliance checklist for aircraft and parts buyers
This is a general checklist, not legal advice. Sanctions law differs by jurisdiction and changes often, so use qualified counsel for any transaction with possible Russian links.
- Trace ownership and registry history of every aircraft and engine, including any period on the Russian register.
- Demand full release documentation for parts, such as EASA Form 1 or FAA Form 8130-3, and check it against the part’s history.
- Screen all counterparties, intermediaries and shipping routes against current sanctions lists in the relevant jurisdictions.
- Be cautious of unusual pricing or routing, such as a scarce part offered far below market through an unfamiliar third-country trader.
- Use independent appraisal and escrow so that value, title and funds are verified by someone with no stake in the deal.
- Keep records of due diligence for every purchase so the decisions can be shown later.
Need independent advice on aircraft, engines or parts?
Safe Fly Aviation supports aircraft and engine sourcing, market intelligence and asset appraisal, with traceability checked before you commit.
Or email info@safefly.aeroFrequently asked questions
How many aircraft does Russia operate in 2026?
Cirium data from April 2026, as reported by AirwayBuzz, counts 838 passenger aircraft across 46 Russian airlines, of which 460 are Western-built Airbus and Boeing types. Rosaviatsiya, the Russian civil aviation regulator, has reported a wider commercial fleet of 1,135 aircraft, of which 1,088 were operational, in figures cited in late 2025. The two numbers differ because they cover different aircraft types and scopes, so always check which one a source is using.
How many Russian aircraft are grounded because of sanctions?
A Kommersant analysis reported by The Moscow Times on 29 June 2026 found that about one-fifth of the aircraft of Russia’s 11 largest airlines were out of service in summer 2026, and nearly 30% once Aeroflot Group is excluded. Azur Air was worst affected at about 74%, followed by Nordwind at about 44% and S7 at about 32%, while Pobeda was flying its whole fleet. Industry experts quoted by Kommersant called the current level manageable but warned it could worsen from 2027.
How does Russia keep Boeing and Airbus aircraft flying without manufacturer support?
Reporting points to a mix of cannibalising parked aircraft for parts, buying components through third-country intermediaries, expanding domestic repair and, in at least one reported case in 2023, sending an Airbus to Iran for maintenance. In February 2025 the US Department of Justice charged three people linked to an Ohio company with exporting about $2 million of aircraft parts to Russia. These workarounds keep much of the fleet flying, but they raise cost, lengthen turnaround times and weaken traceability.
When will the MC-21 enter service?
Not before 2027 on current official statements. Rostec chief Sergei Chemezov said in May 2026 that about one-third of the MC-21-310 certification flight campaign was complete, and that he hoped to finish certification in the first quarter of 2027 and begin mass production in 2027. The MC-21-310 uses the Russian PD-14 engine instead of the Pratt & Whitney PW1400G of the original MC-21-300, and Russian programme dates have slipped repeatedly, so treat them as targets rather than commitments.
What is the status of the Sukhoi Superjet SJ-100?
The SJ-100 is the re-engined, import-substituted Superjet with Russian PD-8 engines in place of the French-Russian SaM146. A production-standard SJ-100 first flew in September 2025. In September 2026 Chemezov said the first production aircraft will be delivered in the second half of 2027, so the 12 SJ-100 deliveries planned for 2026 will be missed. Industry and Trade Minister Anton Alikhanov expects a type certificate in spring 2027.
Has Russia replaced its Western-built fleet with domestic aircraft?
No. Reuters, citing ch-aviation, reported that only 13 new civil aircraft were added between 2022 and 2025, 12 Superjets and one Tu-214, against plans for 127 aircraft in 2023–2025. In response Russian airlines have been returning older types to service, including Tu-204/214, Il-96, An-148 and Boeing 747 aircraft, according to Izvestia as reported in January 2026. The Il-114-300 turboprop received its type certificate on 5 June 2026, but no production aircraft had been confirmed as delivered by mid-August 2026.
Is it legal to sell aircraft parts to Russia?
Generally no. Since February 2022 the EU, the US and the UK have restricted the export of aircraft, engines and parts to Russia, and the EU’s 21st sanctions package, adopted in July 2026, added new bans on metal powders and alloys used in aerospace and drone production. The exact rules differ by jurisdiction, item and end user, so any company handling aircraft or engine parts should take advice from sanctions counsel and verify the full ownership and routing history of every item.
What does the Russian situation mean for lessors, engine buyers and parts traders?
In Safe Fly’s view the main effects are a permanent loss of Russian-registered aircraft from the lessor market, continued pressure on CFM56, V2500 and other mature engine supply, and a higher compliance burden on anyone buying used serviceable material. AerCap alone wrote off 113 aircraft and 11 engines in 2022. Buyers should insist on complete traceability, check ownership history for any Russian registry link, and use independent appraisal before committing to aircraft, engines or parts.
Related reading
This report is based on public sources as of 27 October 2026 and is for general information only. It is not legal, sanctions-compliance or investment advice. Safe Fly Aviation provides independent aviation intelligence and advisory services.