Aircraft Engine Shortages in 2026: MRO Delays and Spare Engine Demand
Updated October 2026 · By Safe Fly Aviation · Commercial aviation market intelligence
Quick answer
Aircraft engine shortages in 2026 are mainly a parts and shop-capacity problem. AerFin reports that CFM56 full overhauls typically take 90–120 days, with high-pressure turbine blades the biggest bottleneck, and IATA says GTF groundings peaked at 648 aircraft in March 2025. Operators should compare buying, leasing, exchanging and overhauling on the full cost of downtime, not on purchase price alone.
These figures come from the sources listed at the end of this article. They measure different things over different periods and should not be compared directly.
01 · Causes
What Is Driving Aircraft Engine Shortages in 2026?
For airlines, lessors and maintenance providers, engine availability is now a fleet-planning issue as much as a maintenance issue. Parts shortages, longer shop visits and limited spare-engine access can keep aircraft out of service for longer than planned. The effect varies by engine type and workscope, so operators should check each case against current maintenance-provider commitments instead of relying on one industry-wide turnaround figure.
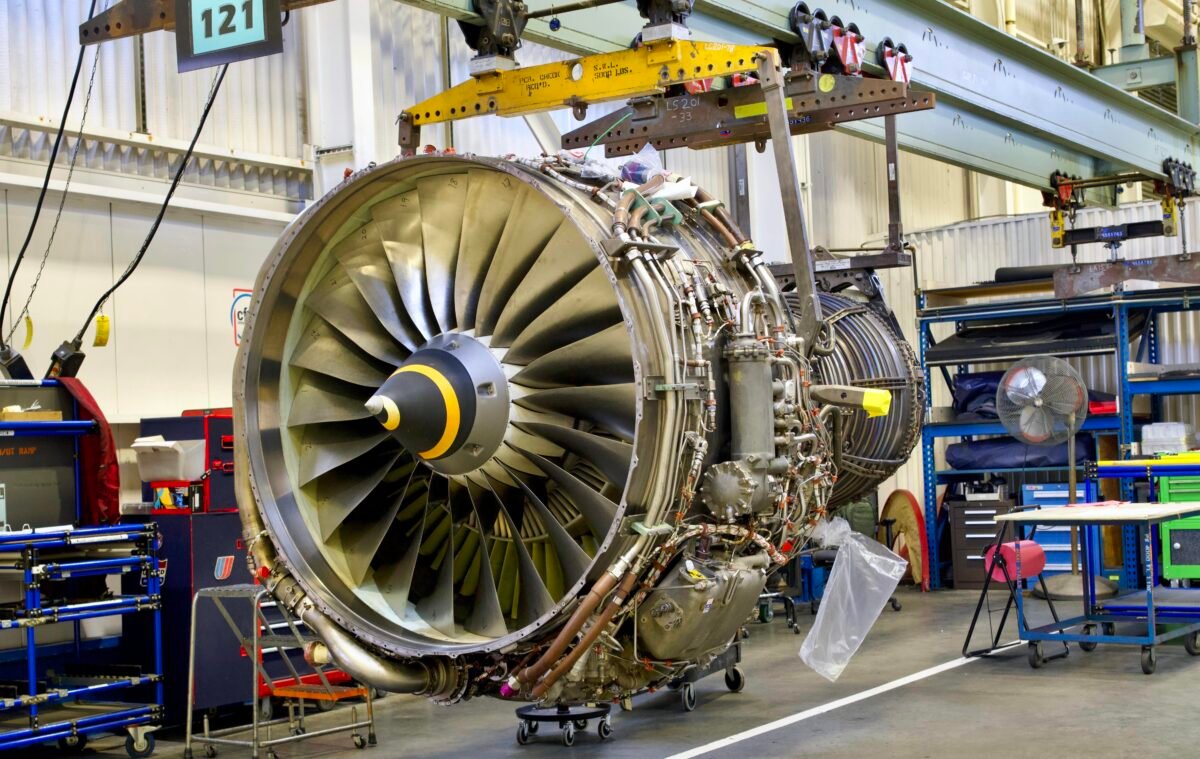
Parts availability can matter as much as shop capacity
In a June 2026 article, AerFin’s vice president of sales, Dave Hobbs, wrote that for the CFM56 the industry-wide shortage of high-pressure turbine (HPT) blades is the single biggest bottleneck. Replacement-part shortages can extend turnaround even when repair capacity is available. Aviation Week reported the same issue on 31 August 2026, noting that supply constraints affect both newly manufactured blades and used serviceable material (USM).
This is a supplier and market-participant view, not a guarantee about every engine or shop. Actual turnaround depends on engine condition, workscope, findings after disassembly, material availability, contract terms and the shop’s workload.
Turnaround depends on engine type and workscope
AerFin’s June 2026 market overview gives the typical ranges below. Treat them as indicative industry commentary, not delivery dates for a specific engine.
| Engine family | Full overhaul range reported | Light work range reported |
|---|---|---|
| CFM56 | 90–120 days | About 45 days |
| V2500 | 60–70 days | About 45 days |
| PW4000 | 120 days or more | About 60 days |
| CF6 | 120 days or more | About 60 days |
| PW1100G-JM (GTF) | 260–365 days | Not given in the source |
Source: AerFin, published by Aviation Business News on 24 June 2026. Ranges can change and may not match an individual shop’s quotation. For the V2500 supply picture, see our V2500 engine supply shortage report.
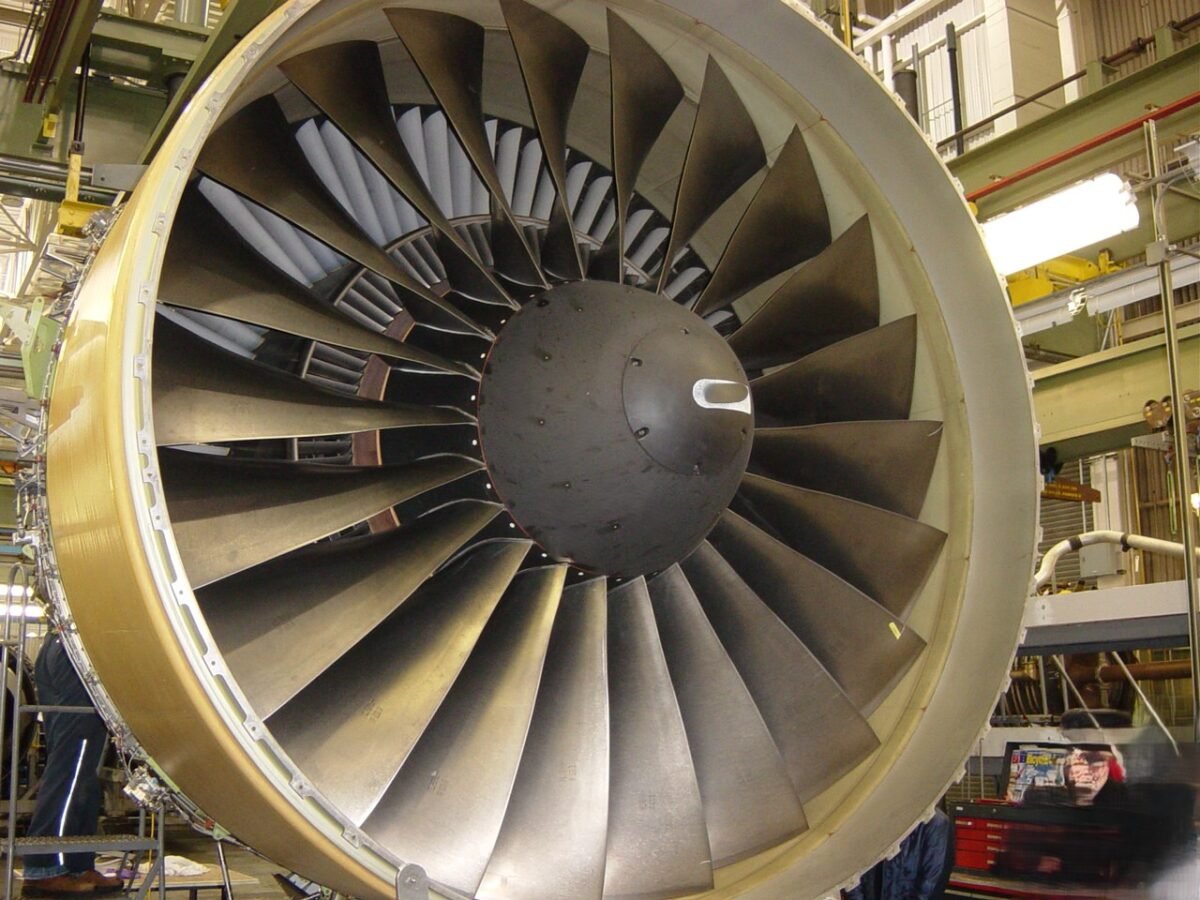

Newer engines have wider fleet effects
IATA’s 24 June 2026 release says 648 Pratt & Whitney GTF-powered aircraft were grounded at the peak in March 2025, 28% of the GTF fleet at that time, while awaiting shop visits, spare engines or parts. It also forecasts annual LEAP shop visits rising from about 600–800 in 2025 to more than 5,000 by 2040. For the GTF it gives around 1,000 rising to more than 2,000 without restating the year.
These are IATA’s published figures and forecasts, not a prediction that every operator will see the same disruption. They do show why airlines and lessors need to build engine support into fleet and capacity plans. Our LEAP-1A aftermarket analysis covers the newer-engine side in more detail.
Aircraft delivery delays add pressure
IATA reports an aircraft backlog of about 17,000 jets and estimates that supply-chain problems will cost airlines more than US$11 billion in 2025. Its breakdown is shown below. These costs cover wider aviation supply-chain effects; they are not engine-overhaul costs alone.
02 · The older fleet
Why the CFM56 Aftermarket Matters
The CFM56 family powers large numbers of older-generation narrowbody aircraft, including Boeing 737 Classic and 737NG variants and Airbus A320ceo-family aircraft. The exact engine model varies by aircraft variant, so confirm the model and configuration before sourcing parts or assessing an engine asset. See our CFM56 engine family guide and CFM56 market report.
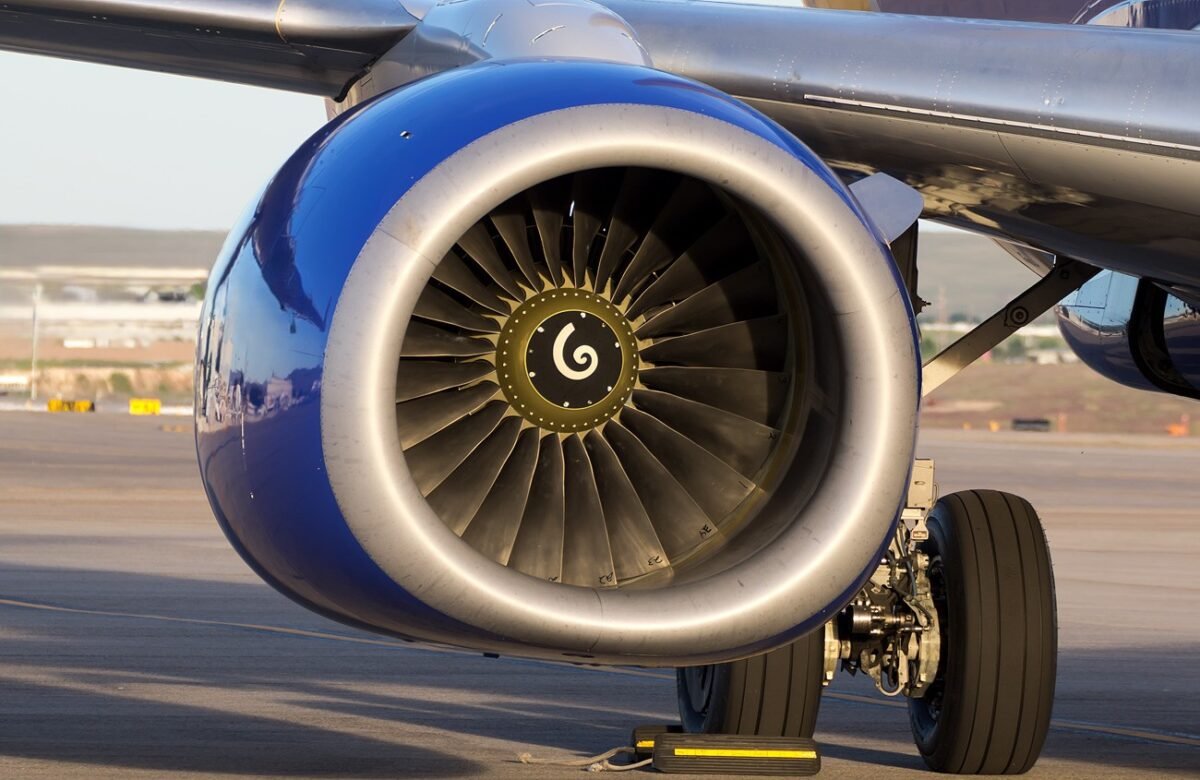

Aviation Week’s 31 August 2026 report, citing AerFin, says blades with around 10,000 or more remaining cycles are increasingly difficult to source on the secondary market, and that scrap rates for blades arriving at overhaul can exceed 50% depending on operating environment and duty cycle. These are conditional market observations, not universal rates for all blades or engines.
The same report says OEM blade-repair turnaround has stayed around 45 days, so the availability of replacement blades is the key constraint. It quotes AerFin as expecting supply to begin improving toward the end of 2026 or early 2027, based on current OEM guidance, while warning that any improvement may take time to reach the supply chain. That is an industry expectation, not a confirmed recovery date.
What operators should take from this
Do not judge an engine only by its headline purchase price or nominal time since overhaul. Review the specific workscope, material status, life-limited parts (LLPs), records, forecast maintenance exposure and the availability of replacement material. Our engine shop visit cost guide sets out what to ask a shop.
03 · The decision
Buy, Lease, Exchange or Overhaul an Engine?
There is no single best answer for every fleet. Compare total cost, expected downtime, asset condition, contract exposure and the operational cost of an aircraft being unavailable.
| Option | Potential benefit | Questions to resolve before committing |
|---|---|---|
| Buy a replacement engine | May give longer-term asset control and a planned maintenance position. | Are the engine records complete? What is the LLP status? What workscope is forecast? Are configuration, title, traceability and release documents acceptable? |
| Lease a spare engine | May bridge an extended shop visit and preserve near-term fleet capacity. | Is the engine available when needed? What are the lease rate, minimum term, return conditions, reserves, installation costs and redelivery obligations? |
| Overhaul the existing engine | May preserve the value of an owned asset and address known technical needs. | What is in the workscope? How are non-routine findings priced? Which parts are available? What schedule assumptions and escalation clauses apply? |
| Engine exchange | A serviceable replacement may keep an aircraft flying while the removed engine is repaired. | Can a suitable replacement be sourced? Are configuration and records compatible? What are the exchange core, condition, timing and commercial terms? |
Engine exchange is not automatically cheaper than a shop visit or a lease. Aviation Week quotes AerFin describing it as one approach gaining momentum, in which operators lease or acquire a serviceable replacement while the removed engine is overhauled. It is worth evaluating where downtime has a material cost and a suitable engine is available. Browse current aircraft engines for sale or ask about engine and APU sourcing.
04 · Action
Practical Steps to Reduce Avoidable Downtime
Plan material before induction
Work with the MRO to identify likely material needs early, especially bottleneck parts. Ask what is in stock, what is subject to repair or replacement, the expected lead times, and what happens if incoming components fail inspection.
Check approvals and records
Approved alternative parts and repairs can be options where applicable, but they are not interchangeable by default. Confirm approved data, release documents and acceptance requirements for your engine.
Book capacity and verify the schedule
Ask for a written plan with induction assumptions, expected findings, material dependencies, milestones and the approval process for extra work. Expect a schedule range until teardown and inspection are complete.
Review spare-engine cover
Compare the cost of owning or leasing spare capacity with the cost of an unplanned removal or a longer shop visit. Scenario comparisons beat assuming a spare will always be available at short notice.
The FAA explains that Parts Manufacturer Approval (PMA) is a design and production approval for eligible replacement or modification articles, and its use must suit the specific product, approval basis and installation. A Designated Engineering Representative (DER) is an individual appointed by the FAA to make or recommend engineering findings within an authorised discipline. A DER is not, by itself, a blanket approval for any repair.
IATA’s June 2026 release sets out four industry-level asks: increase engine parts availability (including faster approval of repair solutions, licensed production of critical components and more access to used serviceable material), ensure fair access to the MRO market, secure long-term access to spare parts with predictable pricing, and have all OEMs adopt transparent, competitive aftermarket principles that support customer choice and regulator-certified alternative parts and repairs. Operators still need to verify what is approved and available for their own engines.
05 · Due diligence
What Buyers and Lessors Should Examine
Market conditions change quickly, and the sources reviewed for this article do not establish a single reliable price trend for every CFM56 variant or maintenance condition. Assess engine value on the individual asset and transaction evidence, not on a broad percentage increase or a general claim that prices have stabilised.
- Technical records and traceability. Check completeness, serial-number consistency, modification status, maintenance history and release documentation. Use our engine records review checklist.
- LLP status. Verify part numbers, cycles, limits, life remaining and the supporting back-to-birth or other required records. See engine LLP management explained.
- Maintenance status. Review the last shop visit, workscope, findings, repairs, test results and forecast next maintenance exposure.
- Material support. Establish whether expected replacement parts and approved repair routes are realistically available.
- Commercial terms. Confirm title, liens, delivery condition, acceptance criteria, warranties or representations, taxes, transport and transaction costs.
When does part-out make sense?
Part-out may be worth evaluating when the cost of restoring an engine to service cannot be justified by its expected remaining economic value. The decision needs a component-level assessment of recoverable material, life status, documentation, repairability, demand, teardown cost and disposal obligations. Not every removed component will be serviceable or saleable, and part-out should not be treated as guaranteed revenue.
06 · Outlook
The Safe Fly Aviation Perspective
The available evidence points to continued pressure on engine maintenance planning. The CFM56 aftermarket faces material constraints, while IATA forecasts a substantial rise in LEAP and GTF shop visits as those fleets grow. Timing and severity will differ by engine, operator and maintenance arrangement.
For airlines, lessors, MRO providers and aircraft owners, the practical response is to plan early, verify technical records, understand material dependencies and compare the full cost of downtime with the available sourcing and maintenance options. Safe Fly Aviation works across engine and spares sourcing, aircraft sales and acquisition, and aviation consultancy. Any specific sourcing requirement should be assessed against the engine model, part number, condition, documentation and applicable approval requirements.
07 · Questions answered
Aircraft Engine Shortages FAQ
Why are there aircraft engine shortages in 2026?
The pressure comes mainly from parts availability and shop capacity, not only from a lack of engines. AerFin describes the shortage of high-pressure turbine (HPT) blades as the single biggest CFM56 overhaul bottleneck, and IATA reports that GTF-powered aircraft were grounded in large numbers while awaiting shop visits, spare engines or parts. Newer LEAP and GTF fleets are also adding shop-visit demand.
How long does an engine overhaul take in 2026?
AerFin’s June 2026 market overview gives typical full-overhaul ranges of 90–120 days for the CFM56, 60–70 days for the V2500, 120 days or more for the PW4000 and CF6, and 260–365 days for the PW1100G-JM geared turbofan. These are indicative industry ranges, not guaranteed delivery dates; actual turnaround depends on workscope, findings after teardown and material availability.
Why are CFM56 HPT blades hard to get?
Aviation Week reports, citing AerFin, that blades with around 10,000 or more remaining cycles are increasingly difficult to source on the secondary market, and that scrap rates for blades arriving at overhaul can exceed 50% depending on operating environment and duty cycle. OEM blade-repair turnaround has stayed around 45 days, so replacement-blade availability is the key constraint.
How many GTF aircraft were grounded?
IATA says 648 Pratt & Whitney GTF-powered aircraft were grounded at the peak in March 2025, which it puts at 28% of the GTF fleet at that time. They were awaiting engine shop visits, spare engines or parts.
Should an airline buy, lease, exchange or overhaul an engine?
There is no single best answer. The choice depends on total cost, expected downtime, asset condition, contract exposure and what an aircraft on the ground costs the operator. Engine exchange is not automatically cheaper than a shop visit or a lease, but it is worth evaluating where downtime is expensive and a suitable engine is available.
What are PMA and DER approvals in engine maintenance?
Parts Manufacturer Approval (PMA) is an FAA design and production approval for eligible replacement or modification articles. A Designated Engineering Representative (DER) is an individual appointed by the FAA to make or recommend engineering findings within an authorised discipline. Neither is a blanket approval: use must match the specific product, approved data and installation, so confirm with your maintenance and regulatory teams.
When will engine supply improve?
Aviation Week quotes AerFin as expecting CFM56 supply conditions to begin improving toward the end of 2026 or early 2027, based on current OEM guidance, while warning that any improvement may take time to work through the supply chain. That is an industry expectation, not a confirmed recovery date.
What should buyers check on a used aircraft engine?
Check the technical records and traceability, life-limited part (LLP) status, last shop-visit workscope and findings, the availability of replacement material and approved repair routes, and the commercial terms such as title, liens, delivery condition and warranties.
References
Sources
- AerFin, “Inside the engine MRO supply chain: why repair delays are rising and what’s driving them”, Aviation Business News, 24 June 2026 (turnaround ranges, HPT blade bottleneck)
- Aviation Week, “HPT Blade Supply Crunch Slows CFM56 Overhauls”, 31 August 2026 (blade availability, scrap rates, exchange, outlook)
- IATA, “Urgent Action Needed to Ease Engine MRO Bottlenecks”, 24 June 2026 (GTF groundings, LEAP and GTF shop-visit forecasts, recommended actions)
- IATA, Aviation Supply Chain (aircraft backlog and estimated 2025 airline supply-chain costs)
- FAA, Parts Manufacturer Approval – Design Approval (PMA scope)
- FAA, Designated Engineering Representatives (DER) (role and scope of DERs)
Market figures and forecasts are attributed to the sources above and can change. Check them again before relying on them for a transaction.
Looking for an Aircraft Engine or Aviation Components?
Share your engine model, part number, required condition, quantity and documentation requirements so the sourcing request can be assessed properly.
Or email info@safefly.aero.